The strategic shift is from recommendation to delegated authority.
Most conversations about agentic commerce begin with the customer experience: an AI assistant finds a product, compares options, builds a basket and removes friction from checkout. That is useful, but it is not the strategic inflection point.
The deeper change begins when the agent is allowed to act. Once software can reserve inventory, commit to a supplier, select a payment method or initiate a payment within delegated rules, the commerce journey stops being only an interface problem. It becomes a fintech, identity, risk and operating-model problem.
Traditional digital commerce was designed around a human clicking a button on a known website or application. Agentic commerce introduces another actor into the transaction. The merchant, issuer, payment provider and enterprise now need to know not only who ultimately owns the money, but which agent acted, what authority it had, what constraints applied and whether the final transaction matched the original intent.
Invisible checkout does not mean simpler payments
If an agent can discover, evaluate and complete a purchase on behalf of a user, the customer may see less of the traditional checkout. That does not mean the payment layer becomes simpler. It means more of the payment decision moves behind the interface.
A conventional checkout can ask the customer to choose a card, authenticate, accept terms and click pay. An agent-led journey may need to make those decisions from policy: use this account for travel, preserve rewards where possible, never buy from an unapproved merchant, do not exceed a defined amount, route high-value purchases for approval and use the cheapest acceptable rail for certain supplier payments.
This turns what used to be a sequence of screens into a sequence of permissions, credentials, rules and machine-readable evidence. The winning infrastructure therefore has to make the invisible transaction more controlled, not less controlled.
Delegation becomes the new checkout
A normal checkout captures an immediate human decision. An agentic transaction may begin much earlier with a delegated instruction: book a suitable flight under a certain budget, replenish inventory when stock reaches a threshold, renew a software subscription if pricing remains within limits, or source a component from an approved supplier.
That means the payment event is no longer the whole authorization story. The system needs to preserve the chain from intent to action. Who instructed the agent? What was it allowed to buy? From which merchants? For how much? Until when? Could it choose another payment rail? Did it need a final human approval above a threshold?
Google's Agent Payments Protocol describes this challenge through signed mandates and verifiable credentials. Mastercard has framed it around registered agents, agentic tokens and verifiable intent. Visa Intelligent Commerce emphasizes secure credentials, controls, authentication and trusted agent identification. The architectures differ, but the operating requirement is converging: delegated commerce needs machine-readable authority.
The agentic payment stack needs five capabilities
I would separate the emerging stack into five layers. They do not all need to sit inside one company, but every serious agentic-commerce architecture will need them.
First is agent identity. A merchant or payment provider needs a reliable way to distinguish a trusted agent from an automated bot, scraper or malicious actor. Second is verifiable user or enterprise intent: a durable record of what the agent was authorized to do. Third is programmable payment authority: credentials, budgets, merchant rules, timing rules and escalation thresholds that an agent can use without exposing unrestricted payment access.
Fourth is orchestration. The transaction may need to choose among cards, account-to-account payments, virtual cards, wallets, real-time payment rails or stablecoin-based settlement depending on geography, cost, merchant acceptance and policy. Fifth is post-transaction evidence: reconciliation, receipts, exception handling, refunds, disputes and an audit trail that explains why the agent acted.
- Trusted agent identity
- Verifiable intent and delegated authority
- Programmable credentials and spending controls
- Multi-rail payment orchestration
- Reconciliation, evidence and exception management
The industry is already rebuilding the trust layer
The most useful signal is not the marketing language around autonomous shopping. It is the infrastructure being built by the major payment and commerce ecosystems.
Visa Intelligent Commerce is developing agent-specific payment tokens, authenticated purchasing instructions, controls and commerce signals so an agent's actions can be checked against the user's original instruction. Visa is also positioning trusted-agent identification and network-agnostic connectivity as part of the operating layer for agent-led commerce.
Mastercard Agent Pay combines registered agents, network-token infrastructure and verifiable user intent. In June 2026, Mastercard extended the model with Agent Pay for Machines, aimed at machine-to-machine and high-velocity programmatic payments.
Google's AP2 establishes a payment-agnostic framework for agent-led payments using signed mandates and verifiable credentials, while the Universal Commerce Protocol creates a common language across discovery, checkout and post-purchase interactions. Stripe, meanwhile, is connecting product discovery, agent checkout, shared payment tokens, agent wallets and machine-payment protocols. Different players are attacking different parts of the stack, but all are solving the same underlying problem: trust when software becomes a transaction initiator.
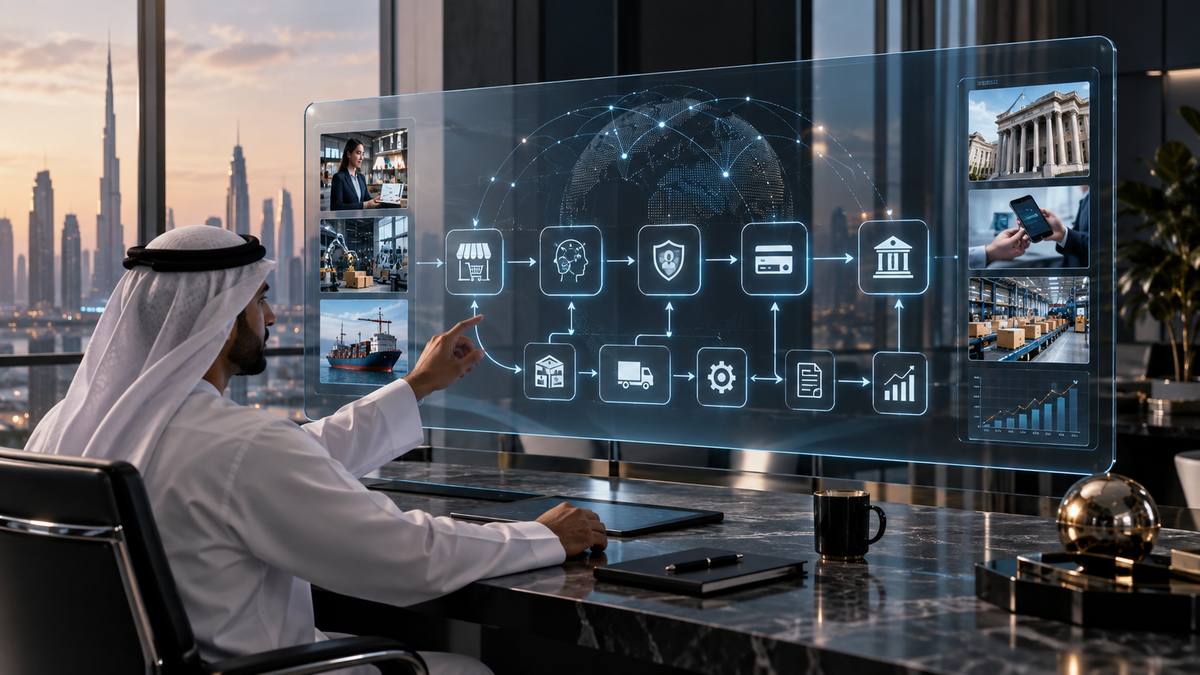
Payment orchestration becomes more strategic, not less
There is a temptation to assume that agents will simplify payments because the customer will see less of the checkout. In practice, hiding the interface can increase the complexity behind it.
An intelligent agent may optimize not only what to buy, but how to pay. A corporate purchasing agent might use a virtual card for one supplier, account-to-account payment for another and a local rail in a third market. A consumer agent may need to preserve card rewards, loyalty benefits or refund protection. A cross-border transaction may need to balance acceptance, foreign exchange, settlement speed, working-capital impact and cost.
The value therefore moves toward infrastructure that can expose payment choices to software in a controlled, machine-readable way. The winning layer is unlikely to be a simple payment button. It is more likely to be an orchestration layer that combines identity, policy, payment connectivity, risk signals and reconciliation.
The enterprise use case may matter before fully autonomous consumer shopping
Consumer shopping attracts attention because it is easy to visualize. The enterprise opportunity is potentially more operationally significant.
Businesses already delegate repeatable commercial decisions to people through policies: approved suppliers, travel limits, procurement thresholds, payment terms, purchase orders and expense rules. Agents can make parts of those workflows continuous. They can monitor inventory, source alternatives, prepare a purchase, choose within approved commercial rules, select the appropriate payment method and route exceptions to a person.
The same logic applies to recurring software spend, cloud consumption, travel, logistics, media buying, maintenance, low-value procurement and supplier payments. In these cases, the fintech opportunity is not only to process the payment. It is to connect commercial intent to money movement while preserving policy, controls and evidence.
B2B agentic payments change the value proposition for fintech infrastructure
In B2B, the payment is often the last step in a longer commercial workflow. Before money moves, the business may need supplier verification, purchase approval, invoice validation, budget control, tax treatment, foreign exchange, payment terms and evidence for reconciliation.
An agent that can participate across that workflow is therefore more valuable than an agent that only sends a final payment instruction. This creates an opportunity for payment platforms and fintech infrastructure providers to move upstream: from transaction processing into policy-aware orchestration.
For an enterprise, the useful proposition is not 'AI can pay bills.' It is: the system can understand the authorized commercial task, select the correct execution path, move money through an approved rail, preserve evidence and reconcile the result back to the business system.
The fintech economics can sit across several layers
Agentic commerce does not create one new revenue stream. It can create a new distribution and control layer across several existing ones.
Transaction revenue can still exist, but the higher-value economics may sit in orchestration, foreign exchange, programmable credentials, fraud and risk services, compliance, treasury connectivity, reconciliation software and enterprise control planes. A fintech that becomes the trusted execution layer for an enterprise agent can participate in more of the workflow than a provider that only appears at the final payment instruction.
This is particularly relevant in B2B and cross-border flows, where the payment itself is only one component of a broader commercial process involving approvals, invoices, supplier identity, payment terms, FX, settlement and reconciliation.
- Payment and transaction fees
- FX and cross-border economics
- Orchestration and intelligent routing
- Programmable virtual credentials
- Risk, fraud and compliance services
- Treasury, reconciliation and enterprise workflow software
A useful architecture separates the control plane from the execution plane
One way to make the operating model clearer is to separate the control plane from the execution plane.
The control plane holds identity, policy, mandates, budgets, merchant rules, approval thresholds, compliance requirements and the evidence that defines what an agent is allowed to do. It should be deterministic wherever the consequences are material. The execution plane then connects to payment rails, wallets, cards, account-to-account networks, treasury systems, merchants and settlement infrastructure.
AI can help interpret intent, evaluate options and recommend a route, but money movement should still be bounded by explicit controls. This separation makes the system easier to audit, easier to revoke and less dependent on any one model.
- Control plane: identity, mandates, policy, limits, approvals and risk rules
- Execution plane: payment rails, credentials, FX, settlement and merchant connectivity
- Evidence layer: receipts, mandates, transaction context, exceptions and reconciliation
- Human authority: approval and escalation for high-consequence actions
Risk moves from 'is this card valid?' to 'was this agent authorized to do this?'
Agentic payments add a new dimension to fraud and dispute management. A transaction may use a valid credential and still be wrong because the agent exceeded its mandate, misunderstood the task, used the wrong merchant or acted on stale information.
That means risk models need more context. Payment providers may need signals about the agent, the user or enterprise mandate, the transaction modality, the merchant, the path by which the decision was made and whether the final transaction remained inside the authorized constraints.
The dispute model also changes. The evidence packet may need to show the original intent, the agent's authority, the selected offer, the payment instruction and the final settlement. Auditability becomes part of the product, not a back-office afterthought.
The GCC opportunity is an operating-model opportunity
For GCC banks, payment companies, telecom operators, marketplaces, travel businesses and large enterprises, I would not start by asking whether to launch an AI shopping agent.
I would start with commercial workflows where the organization already has a strong payment relationship and a clear permission model. A bank can think about delegated purchasing controls for business customers. A payment platform can expose controlled multi-rail payment capabilities to enterprise agents. A marketplace can make catalogue, pricing, stock and checkout machine-readable while preserving seller and customer protections. A telecom or loyalty ecosystem can connect identity, rewards and payments to agent-led journeys.
The regional advantage will come from solving trust and interoperability across existing ecosystems rather than building another isolated conversational interface. The GCC already has concentrated banking relationships, strong mobile adoption, large enterprise buyers, major travel and hospitality ecosystems and increasingly sophisticated digital commerce. Those characteristics create practical places to test agent-led transactions under clear controls.
The first 90 days should be an evidence programme, not an autonomous-commerce launch
Agentic commerce is developing quickly, so the wrong response is to over-engineer for a future standard that may change. The better response is to identify which capabilities have value regardless of which protocol becomes dominant.
In the first 30 days, map the high-frequency commercial workflows, existing payment rails, approval rules, identity controls and reconciliation gaps. Select one narrow journey where the authority is already explicit. Days 31 to 60 should expose the required data and payment capabilities through controlled APIs, define a machine-readable mandate and run the agent in recommendation or shadow mode.
Days 61 to 90 should allow bounded execution for a small cohort with strict limits, human escalation and full audit. Measure authorization accuracy, transaction completion, exception rate, fraud or loss, reconciliation time, cost per transaction and the share of actions that require human override.
The goal is not to prove that an agent can buy something. The goal is to prove that the complete chain from intent to money movement is controllable, explainable and economically worthwhile.
What an executive dashboard should show
The executive view should connect adoption to trust and economics. Counting agent-initiated transactions is not enough.
I would track the proportion of eligible transactions successfully executed, the percentage that remain within mandate without human intervention, payment authorization rate, fraud and dispute outcomes, average routing cost, FX or payment economics, reconciliation cycle time, manual exception cost and the incremental commercial value created by the agent-led workflow.
The scale gate is simple: expand only when automation increases useful commercial throughput without weakening control, customer protection or unit economics.
- Eligible agent-led transactions and completion rate
- Mandate compliance and human override rate
- Authorization, fraud, dispute and refund outcomes
- Payment and FX cost by rail
- Reconciliation cycle time and exception cost
- Incremental contribution from the automated workflow
My operating view
Agentic commerce will not eliminate fintech. It will make the fintech layer more embedded and more demanding.
The user may see less checkout, but the infrastructure will need more identity, more control, more interoperability and better evidence. The strategic opportunity is to become the trusted transaction layer between human or enterprise intent and autonomous execution.
That is where agentic commerce becomes more than an AI feature. It becomes a new operating model for moving money.
Key takeaways
- The key shift is from AI recommendation to delegated transaction authority.
- Agentic payments require identity, intent, programmable controls, orchestration and auditability.
- B2B procurement and enterprise workflows may be at least as important as consumer autonomous shopping.
- Payment orchestration becomes more valuable when agents can choose among rails, credentials and commercial rules.
- The strongest fintech position may be the trusted execution layer between commercial intent and money movement.
- Start with bounded enterprise workflows and expand only after control, economics and reconciliation are proven.
Frequently asked questions
What is agentic commerce?
Agentic commerce is a commerce model in which AI agents can perform parts of the buying process on behalf of consumers or businesses, including discovery, comparison, decision support and, when specifically authorized, transaction execution.
Why are payments difficult for AI agents?
Traditional payment flows usually assume a person is directly initiating the transaction. Agentic flows add questions about agent identity, delegated authority, spending limits, merchant trust, fraud, liability and proof that the completed transaction matched the user's intent.
Will agentic commerce require new payment rails?
Not necessarily. Much of the early infrastructure is designed to work with existing rails while adding new layers for agent identity, tokenization, mandates, controls and data exchange. Agents may also use real-time payments, stablecoins and other machine-friendly rails where they improve the economics or operating fit.
Where is the strongest enterprise opportunity?
Repeatable commercial workflows with clear policies are attractive starting points: procurement, travel, subscription management, supplier payments, expense, logistics and low-value purchasing. The agent can automate within defined limits and route exceptions to people.
What should a fintech build first?
Start with machine-readable authorization, agent identity, controlled payment credentials, multi-rail connectivity and evidence for reconciliation. These capabilities improve embedded and enterprise payments even before fully autonomous commerce becomes mainstream.
Sources and further reading
- Visa Intelligent CommerceVisa
- Visa Intelligent Commerce for AI AgentsVisa Developer
- Mastercard Agent PayMastercard
- Mastercard launches Agent Pay for MachinesMastercard
- Powering AI commerce with the new Agent Payments Protocol (AP2)Google Cloud
- Under the Hood: Universal Commerce Protocol (UCP)Google Developers Blog
- Stripe Agentic CommerceStripe
Sources support the external facts and frameworks referenced above. The operating interpretation and recommendations are Muhammad Haris Aslam's.